
Since April 2026, Horace Mann Educators has been in a holding pattern, posting a small return of 3.2% while floating around $45.80. The stock also fell short of the S&P 500’s 12% gain during that period.
Is now the time to buy Horace Mann Educators, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Horace Mann Educators Will Underperform?
We don’t have much confidence in Horace Mann Educators. Here are three reasons you should be careful with HMN, plus one stock we’d rather own.
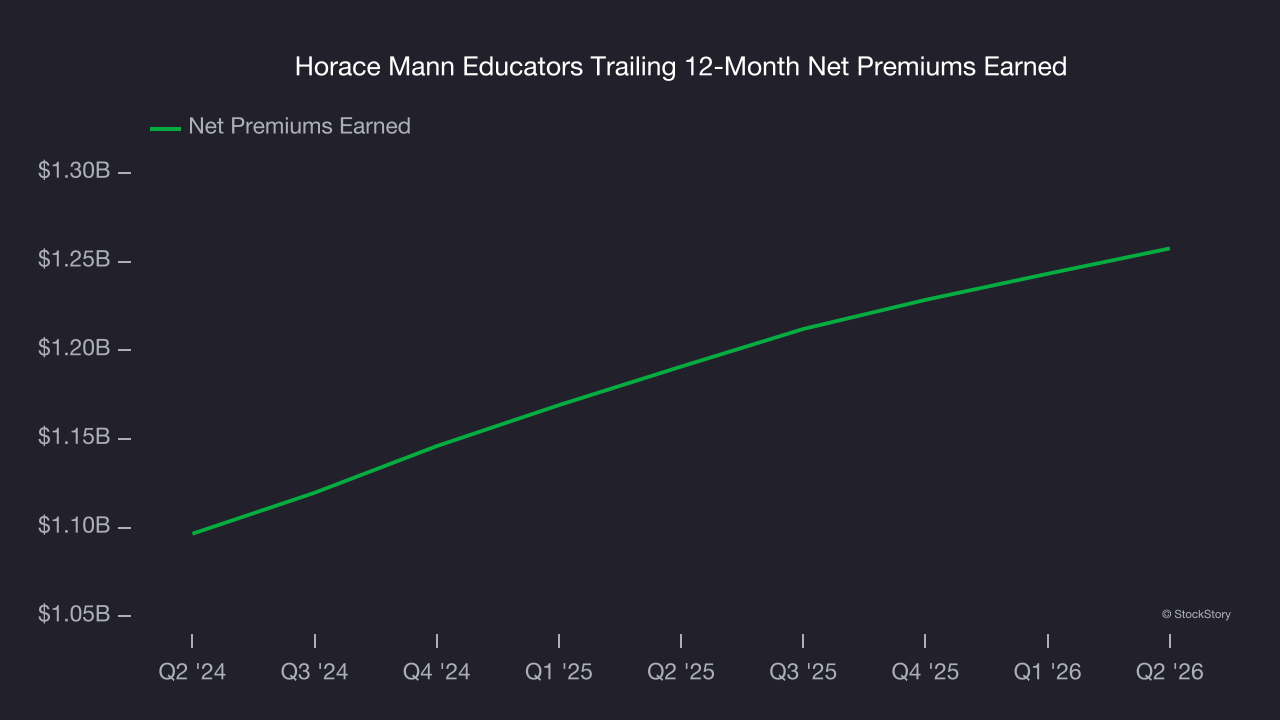
1. Net Premiums Earned Point to Soft Demand
Net premiums earned are net of what’s paid to reinsurers (insurance for insurance companies), which are used by insurers to protect themselves from large losses.
Horace Mann Educators’s net premiums earned has grown at a 6.4% annualized rate over the last five years, slightly worse than the broader insurance industry.
2. Substandard BVPS Growth Indicates Limited Asset Expansion
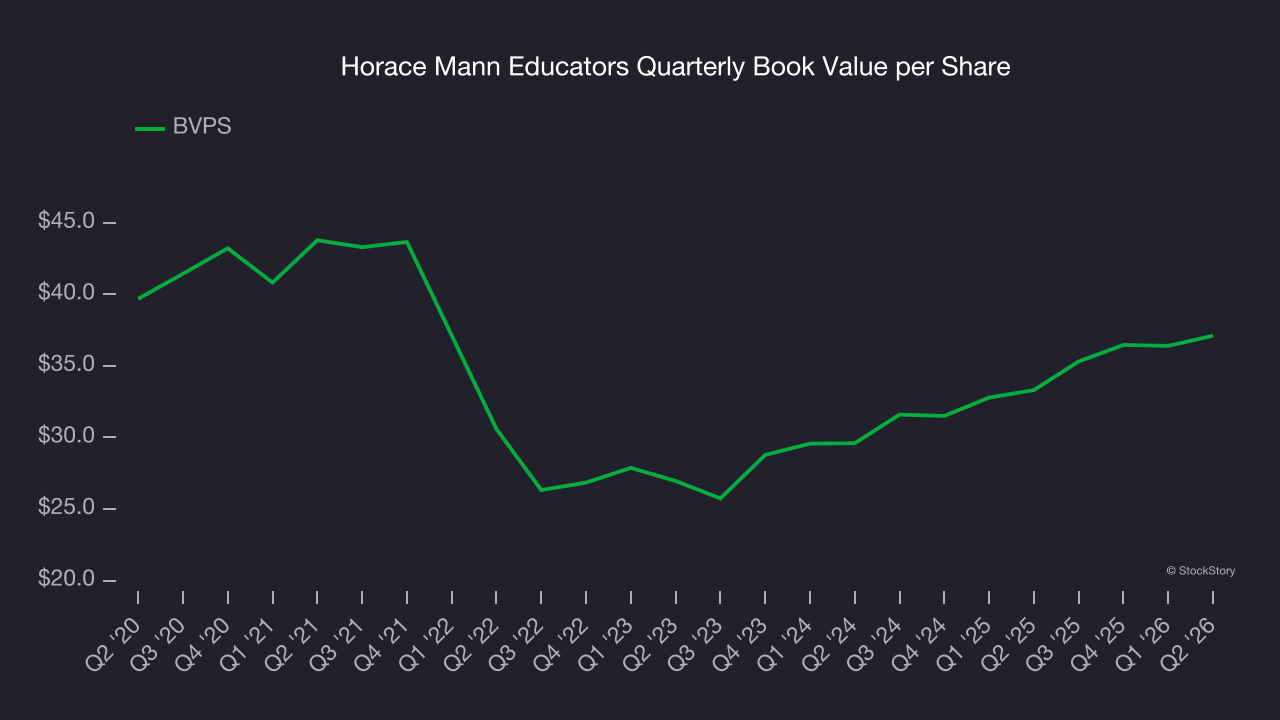
We consider book value per share (BVPS) a critical metric for insurance companies. BVPS represents the total net worth per share, providing insight into a company’s financial strength and ability to meet policyholder obligations.
Disappointingly for investors, Horace Mann Educators’s BVPS grew at a mediocre 12% annual clip over the last two years.
3. Previous Growth Initiatives Haven’t Impressed
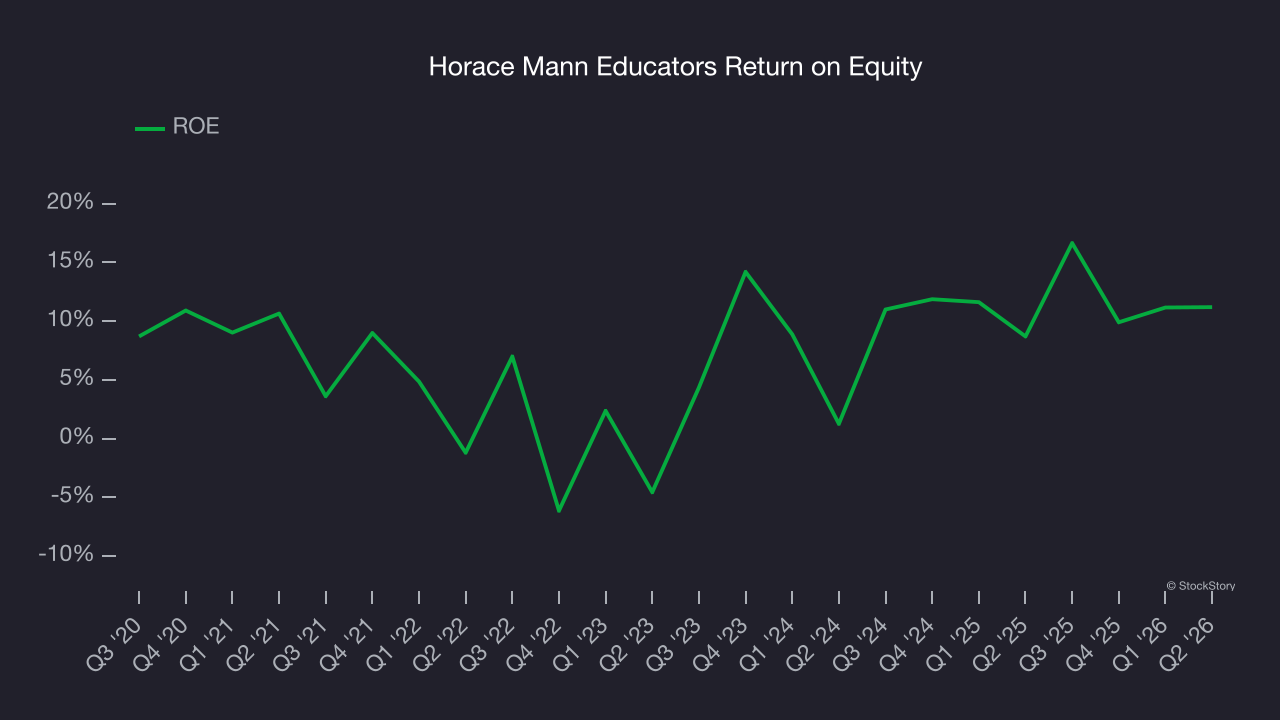
Return on Equity, or ROE, ties everything together and is a vital metric. It tells us how much profit the insurer generates for each dollar of shareholder equity entrusted to management. Over a long period, insurers with higher ROEs tend to compound shareholder wealth faster through retained earnings, buybacks, and dividends.
Over the last five years, Horace Mann Educators has averaged an ROE of 6.8%, uninspiring for a company operating in a sector where the average shakes out around 12.5%.
Final Judgment
Horace Mann Educators doesn’t pass our quality test. With its shares lagging the market recently, the stock trades at 1.2× forward P/B (or $45.80 per share). This valuation multiple is fair, but we don’t have much confidence in the company. There are better stocks to buy right now. Let us point you toward a dominant aerospace business that has perfected its M&A strategy.
Stocks We Would Buy Instead of Horace Mann Educators
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.